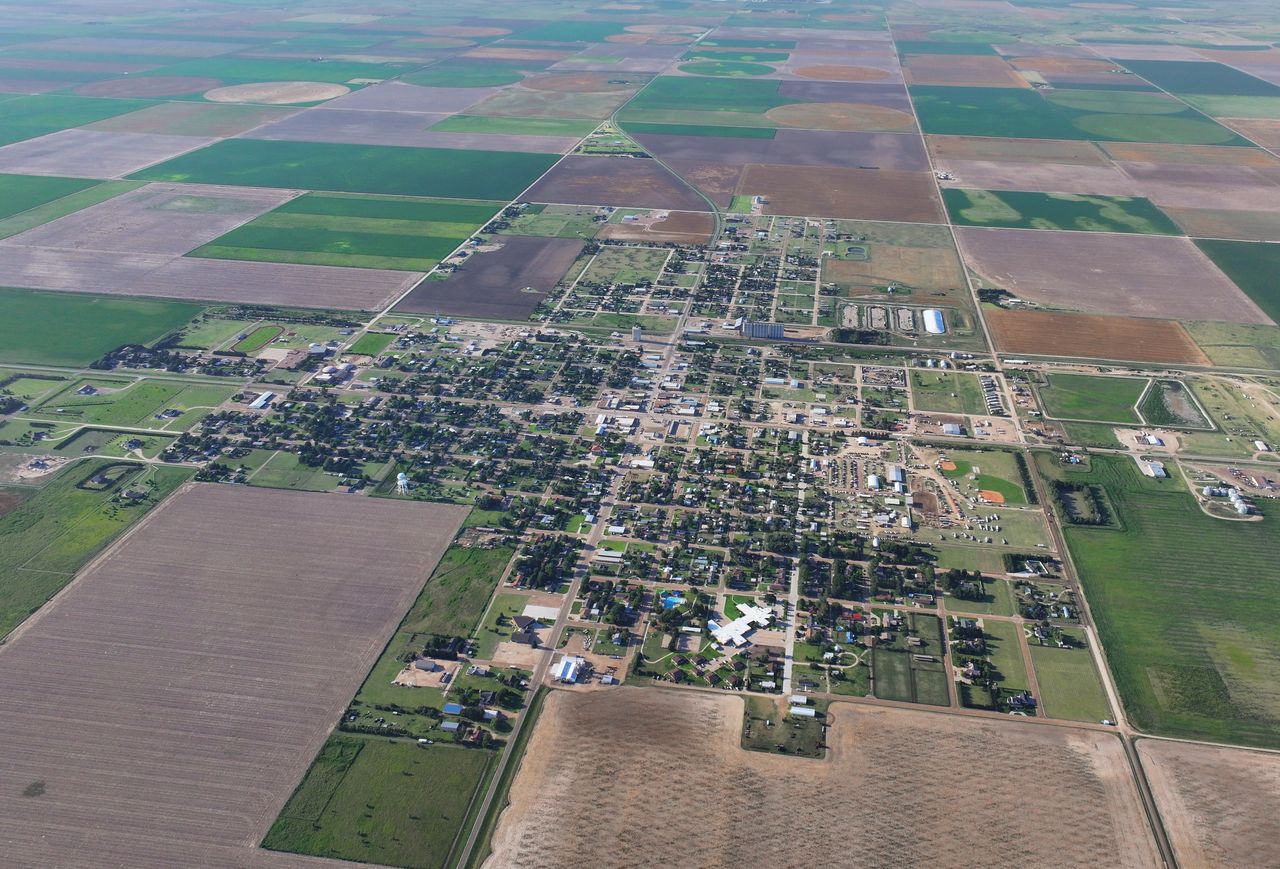
Overview
The City of Leoti ended 2025 with $4,691,609 in unencumbered cash for the total reporting entity (memorandum only, excluding agency funds), down from $5,057,820 at the start of the year, after expenditures of $3,571,994 exceeded receipts of $3,205,783. The General Fund closed at $504,713 unencumbered, with $618,583 in cash. The Water Operating Fund’s $1,198,355 in expenditures — against $668,321 in receipts — accounts for most of the entity’s decline, while the Water Reserve Fund still holds $1,746,807. Total contractual indebtedness was $670,897. After December 31, 2025, the city approved equipment and projects totaling $348,475. No jurisdiction color palette was identified from an official site or seal, so this page uses the neutral default theme.
At a glance
Basis: audited, year ended December 31, 2025. State-portal file labeled “(In Process)”.
Funds
| Fund | Beginning | Receipts | Expenditures | Ending unencumbered |
|---|---|---|---|---|
| Total reporting entity (memorandum only, excl. agency funds) | $5,057,820 | $3,205,783 | $3,571,994 | $4,691,609 |
| General Fund | $518,485 | $1,521,694 | $1,535,466 | $504,713 |
| Special-purpose funds, total | $1,607,477 | $303,678 | $327,269 | $1,583,886 |
| Business funds, total | $2,931,858 | $1,380,411 | $1,709,259 | $2,603,010 |
| Water Operating | $880,569 | $668,321 | $1,198,355 | $350,535 |
| Water Reserve | $1,546,807 | $200,000 | $0 | $1,746,807 |
| Sanitation Operating | $58,534 | $275,425 | $278,047 | $55,912 |
| Sewer Operating | $51,916 | $202,845 | $228,874 | $25,887 |
General Fund walk: $518,485 + $1,521,694 − $1,535,466 = $504,713; with $113,870 in payables, ending cash is $618,583. Certified General Fund budget was $1,538,200; actual expenditures were $2,734 under budget. Entity component ties: beginning $518,485 + $1,607,477 + $2,931,858 = $5,057,820; receipts $1,521,694 + $303,678 + $1,380,411 = $3,205,783; expenditures $1,535,466 + $327,269 + $1,709,259 = $3,571,994. Entity ending cash $4,818,629 (outstanding encumbrances and payables $127,020).
General Fund detail
Receipts, 2025 actual (sum-checks to $1,521,694):
| Receipt | Amount |
|---|---|
| Ad valorem tax | $566,973 |
| Delinquent tax | $6,318 |
| Motor vehicle tax | $109,790 |
| Recreational vehicle tax | $1,376 |
| Sales and compensating use tax | $185,403 |
| Local alcohol tax | $848 |
| Franchise taxes | $108,430 |
| Contractual | $38,391 |
| Licenses and permits | $6,008 |
| Sale of assets | $3,206 |
| Fines and forfeitures | $2,751 |
| Miscellaneous | $31,746 |
| Interest on idle funds | $191,704 |
| Transfer from Equipment Reserve | $88,750 |
| Transfer from Sanitation Operating | $80,000 |
| Transfer from Sewer Operating | $100,000 |
| Total receipts | $1,521,694 |
Expenditures by group, 2025 actual (sum-checks to $1,535,466): General government $490,538 (personnel $235,827 + contractual $191,309 + commodities $63,402; prior-year capital outlay was $112,500); Appropriations $72,050 (Airport $1,400; Cemetery $1,400; Wichita County Economic Development $42,750; Golf Course $20,000; Historical Society $6,500); Public safety $258,596 (Law enforcement $90,000; Fire department $168,596); Public works $404,773; Parks $30,000; Municipal court $43,428; Transfers out $236,081 (Capital Improvement General $95,000; Fire Equipment Reserve $132,704; Opioid Settlement $8,377).
Debt
Contractual indebtedness at December 31, 2025:
| Obligation | Outstanding | Terms |
|---|---|---|
| General obligation refunding and improvement bond | $650,260 | 2.75%, issued February 11, 2015; original $2,675,000; matures February 11, 2037; interest paid $30,195 |
| Finance lease — Edmunds GovTech | $20,637 | 4.18%, issued December 16, 2024; original $90,745; matures October 31, 2026; interest paid $1,883 |
| Total contractual indebtedness | $670,897 | Beginning $1,185,988 less reductions $515,091; interest paid $32,078 |
Debt service due in 2026: $88,597 (principal $69,852 + interest $18,745). Total principal and interest to maturity: $788,357 ($670,897 + $117,460). The note states that debt outstanding does not exceed the K.S.A. 10-308 limit (30% of assessed tangible valuation). KPERS contributions were $42,444 in 2025; the city’s net pension liability share of $335,230 is disclosed in the notes but not reported in the statement under KMAAG.
Sources & notes
All figures sum-checked against the source document: entity component ties, General Fund walk, General Fund receipts detail, and General Fund expenditure groups all tie exactly to their printed totals. The state-portal file is labeled “(In Process)”; the figures above are those in the filed document.